Questions or registration help?(608) 444-6575support@powerofinterest.com
Advanced free calculator

Seller Financing & Owner Financing Calculator

Model a seller-financed note from sale price through balloon payoff. Calculate the note payment, balloon balance, interest collected, total seller cash, present value at an investor yield, and implied yield from a proposed note purchase price.

Calculator reviewed: October 6, 2026•Developed and published by ERICH Incorporated•Loan & interest software since 1999

Your calculated results

The sample values calculate automatically. Change any input to evaluate your own scenario.

Need to take this calculation further?

Manage the seller-financed note after closing

Post actual payments, track current and historical balances, monitor due dates, calculate payoff amounts, and prepare year-end principal and interest totals for one or more private loans. $99 one-time purchase.

One-time purchase · No subscription · Secure payment through PayPal · Free evaluation available · Refund policy · License terms

Seller-financing calculations are estimates. Contracts may use different compounding, payment dates, late charges, servicing costs, taxes, prepayment terms, and legal requirements. Note valuation also depends on credit, collateral, documentation, seasoning, and marketability.

From quick calculation to working file

Managing the note after it closes?

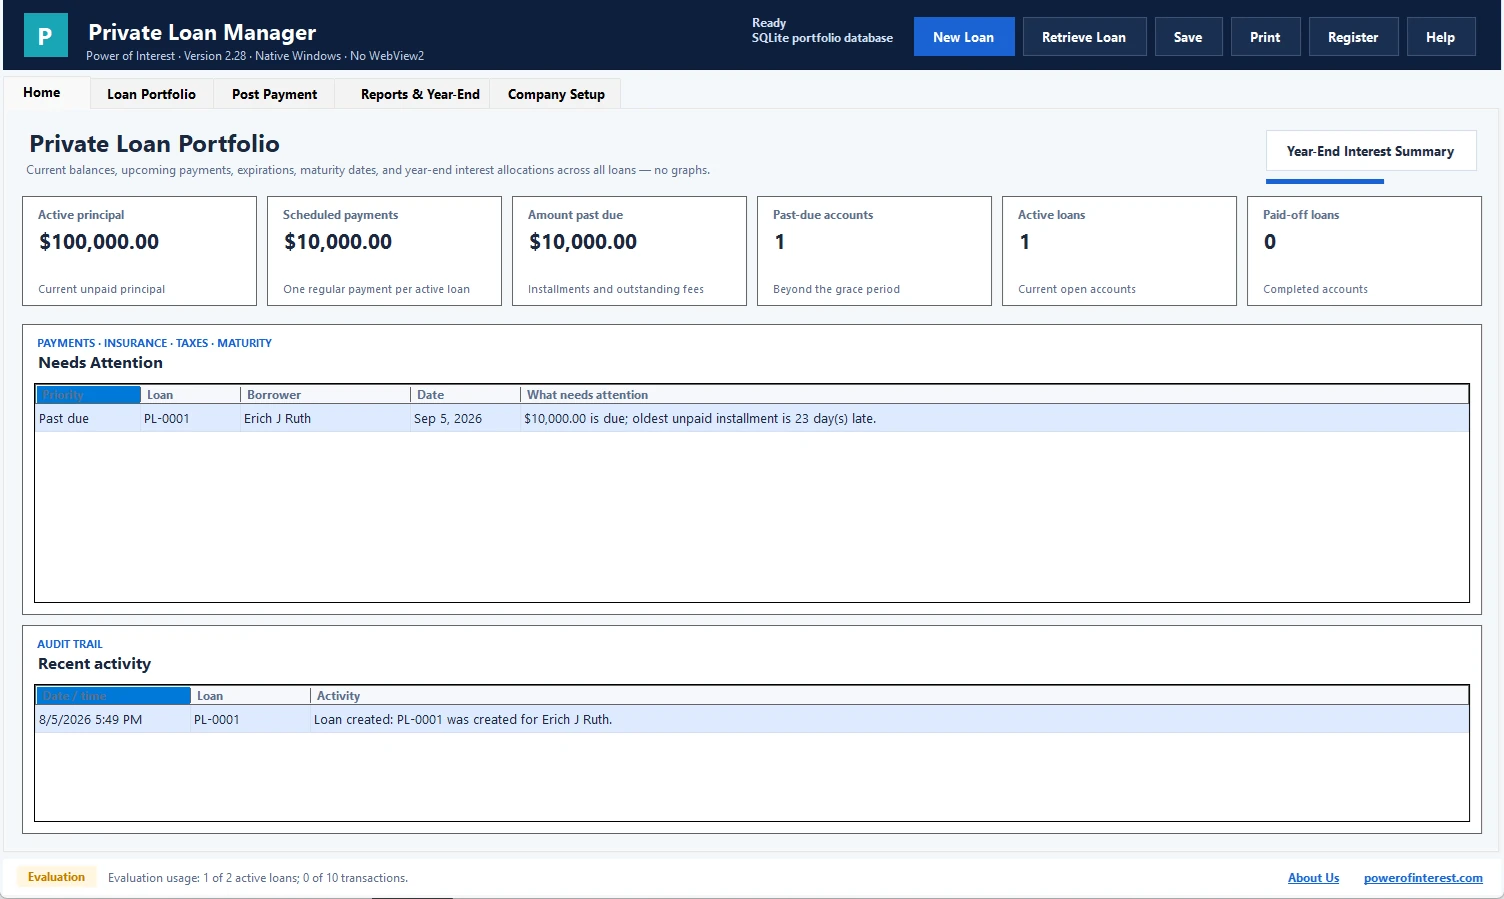
A seller-financed note quickly becomes an ongoing recordkeeping job. Private Loan Manager tracks the loan after closing: actual payments, balances, due dates, payoff information, and year-end totals.

  • Track actual borrower payments
  • See balances and due dates
  • Maintain a payment ledger
  • Create payoff and year-end reports
$99 one-timeNo subscription

Try the evaluation before buying. One-time license; no monthly subscription.

Private Loan Manager Windows dashboard showing loan portfolio and payment tracking
Actual Windows software

Two calculations in one

Structure the note, then value the cash flow

The first part of the calculator determines the payment and balloon from the sale terms. The second part treats the resulting payment stream as an investment and discounts those payments at a target yield.

Note value = PV of scheduled payments + PV of balloon

If the investor's required yield exceeds the note rate, the present value will generally be below the face amount financed.

Balloon notes separate payment term from amortization term

A note can use a 30-year amortization payment but require all remaining principal after five years. The payment is therefore much lower than a five-year fully amortizing payment, while a substantial balloon remains due.

Need the complete note schedule?

Amortization Pro can create, save, edit, print, and export the full payment schedule behind the seller-financing calculation.

More ways to use this calculator

Common calculation questions this page answers

Owner Financing Calculator

Owner financing and seller financing describe the same basic structure: the seller accepts a note instead of receiving the entire price in cash at closing. Use the calculator to model the financed balance, rate, payment, and balloon.

Seller Financing Payment Calculator

The periodic payment depends on the financed amount, interest rate, payment frequency, and amortization term. A separate balloon term can require the unpaid balance before the full amortization period ends.

Seller Financing Balloon Calculator

A balloon note can use, for example, a 30-year amortization schedule but require the remaining principal after five years. The calculator shows the projected balloon balance at the selected balloon date.

Value a Seller-Financed Note

If the seller plans to sell the note, compare the note cash flow with a target investor yield. The present-value calculation can estimate what that payment stream and balloon are worth at the selected yield.

See the full workflow in the seller financing guide. To track payments after closing, use Private Loan Manager.

Frequently asked questions

What is seller financing?

Seller financing is a transaction in which the seller accepts a promissory note for some or all of the purchase price instead of receiving the entire amount in cash at closing.

Is seller financing the same as owner financing?

The terms are commonly used interchangeably to describe financing provided by the property seller or owner.

How is a seller-financed payment calculated?

The payment is based on the financed principal, interest rate, payment frequency, and amortization term.

How is the balloon balance calculated?

The calculator amortizes the note through the balloon date and reports the principal remaining after the scheduled payments made before that date.

Can a 30-year amortization have a five-year balloon?

Yes. The payment can be calculated using a 30-year amortization while the note requires the remaining balance to be paid after five years.

How do you value a seller-financed note?

Discount the future scheduled payments and balloon at the investor target yield. The resulting present value estimates the note value at that yield.

How does the down payment affect seller financing?

A larger down payment reduces the amount financed, which generally lowers the payment, balloon balance, and total interest paid to the seller.